
How redlining affected homeownership in the United States

When people hear the word redlining, they often imagine a single policy designed to exclude one group of people.
The real history is more complicated, and more rooted in economics, risk, and how lending worked at the time.
This post explains what redlining was, who it affected, and why it happened, using documented facts and historical context.
What redlining actually was
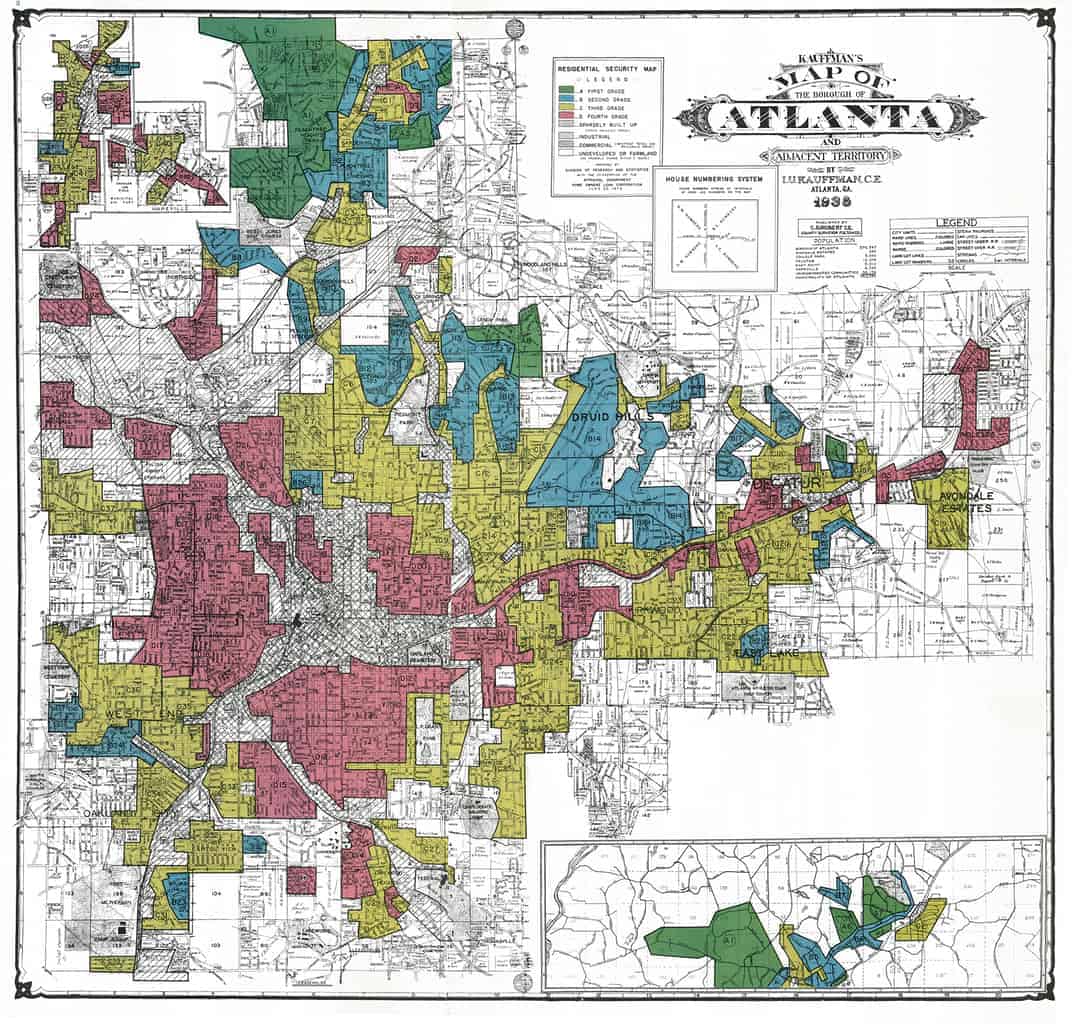

Redlining refers to a set of housing and lending practices, mostly from the 1930s through the 1960s, when neighborhoods were graded based on how risky they were thought to be for mortgage lending.
The most well-known maps were created in the 1930s by the Home Owners’ Loan Corporation (HOLC) as part of the New Deal. These were called Residential Security Maps.
Neighborhoods were graded like this:
- A (Green): Best
- B (Blue): Still desirable
- C (Yellow): Definitely declining
- D (Red): Hazardous
Banks and insurers often used these maps when deciding where to lend.
Important fact:
HOLC itself mostly refinanced existing loans, private lenders used the maps to guide new lending.
How neighborhoods were graded
Neighborhood grades were based on a mix of economic and demographic factors, including:
- Age and condition of homes
- Crowding and density
- Homeownership vs. rentals
- Income stability
- Proximity to factories or railroads
One factor that appears repeatedly in historical documents is the presence of certain racial or ethnic groups. At the time, lenders believed that neighborhoods with rapid population change or cultural “mixing” were more financially risky.
This belief was explicitly written into appraisal manuals.
That doesn’t make it right, but it explains how decisions were justified at the time.
Were only Black neighborhoods redlined?
No. Many non-Black groups were also redlined, including:
- Italian Americans
- Jewish Americans
- Irish Americans
- Eastern European immigrants
- Mexican Americans
- Asian Americans
In cities like New York, Boston, Chicago, and Philadelphia, entire Italian and Jewish neighborhoods were marked as “declining” or “hazardous,” even though residents were white. You can look up redlining by ethnic group at this site.
Redlining was ethnic and class-based, not only racial.
Why lenders believed this was about economics
To understand redlining, you have to understand the lending world of the early 20th century.
At the time:
- There was no modern credit scoring
- Most mortgages were short-term (5–10 years)
- Down payments were large
- A housing crash was still fresh in memory
Lenders believed that property values depended on stability:
- Stable income
- Stable population
- Stable housing use
When neighborhoods experienced:
- Rapid turnover
- Inflows of poorer residents
- Subdivision of homes
- Higher rental concentration
Lenders saw this as higher default risk.
This thinking was framed as risk management, not moral judgment.
Did home values actually fall when neighborhoods changed?
Often, yes, but it wasn’t just about who moved in.
What typically happened was a chain reaction:
- Credit became harder to get
- Homeowners deferred maintenance
- Homes were subdivided to afford rising costs
- Municipal services lagged
- Property values declined further
In many cases, credit withdrawal came first, and decline followed. In this way, it was a self-fulfilling prophecy: the determination of a district as not credit-worthy led to it’s demise, not the other way around.
This created a self-reinforcing cycle that trapped neighborhoods without access to capital.
The role of federal housing policy
The Federal Housing Administration (FHA) played a major role in shaping mortgage markets.
Early FHA underwriting manuals:
- Favored new construction
- Favored uniform neighborhoods
- Warned against insuring loans in areas with “inharmonious” populations
As a result:
- Older urban neighborhoods lost access to capital
- Suburban developments gained it
- Suburbs were built around uniformity, not diversity
Again, this was framed as financial stability, not social policy, but the impact was real.
What about the GI Bill?
The GI Bill itself did not explicitly deny benefits to specific veterans.
However:
- It was administered locally
- Loans still depended on banks, appraisers, and sellers
- Access varied widely by location
This meant that benefits were unevenly available, even when they were legally allowed.
So while the federal government guaranteed loans, private banks still decided whether to lend, and they relied on:
-
FHA underwriting manuals
-
Appraisal standards
-
Neighborhood “risk” grades
-
Local norms and prejudice
Which put the results in the hands of local lenders where discrimination could and did occur for many ethnic groups.
When did redlining officially end?
Formal redlining ended with major civil rights and housing laws:
- The Fair Housing Act of 1968 outlawed housing discrimination
- Appraisal standards were rewritten
- Race and ethnicity were removed from underwriting
- Credit scoring slowly replaced neighborhood-based assumptions
Modern mortgage lending works very differently than it did 80 years ago.
Conclusion
Redlining:
- Was real
- Affected many groups, not just one
- Was justified at the time as economic risk management
- Became self-fulfilling by cutting off access to capital
- Is no longer legal or used in modern lending
- Prevented groups from building intergenerational wealth due to discrimination
Understanding this history helps explain why housing patterns look the way they do today, and why some groups benefitted from homeownership more than others.
If you think you’ve been discriminated against for housing, here is how to file a complaint.
Leave A Comment